Author: LBank Research Analyst: Ludo
Disclaimer: This report is compiled and analyzed from publicly available information and is intended solely for information sharing and research discussion. It does not constitute investment advice, a securities recommendation, a trading instruction, or any guarantee of returns. The company operations, valuations, market prices, and consensus expectations discussed herein may change over time. Readers should independently verify the data and make their own decisions.
1. Core Conclusion
Overall judgment: Micron Technology Inc. is now a higher-quality memory supplier than it was in prior cycles, and the shares appear reasonably valued with a positive risk-reward skew, but the decisive variable is whether multi-year Strategic Customer Agreements can preserve an earnings floor after the current 86% gross-margin peak normalizes.
-
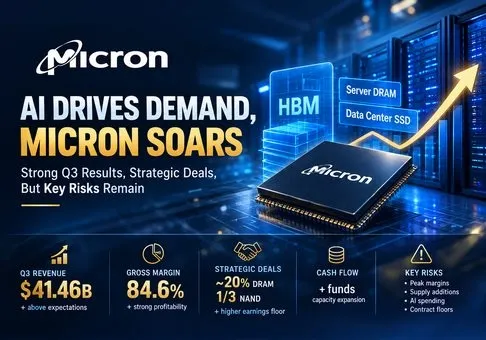
The business has moved from cyclical recovery to scarcity economics. Fiscal Q3 2026 revenue reached USD 41.46 billion, up 74% sequentially and 346% year over year, while GAAP gross margin expanded to 84.6%. DRAM average selling prices rose in the low-60% range sequentially and NAND prices rose in the mid-80% range, whereas bit shipments increased only low single digits and mid-single digits, respectively. The investment implication is that pricing, not volume, created most of the earnings step-up; this is exceptionally profitable but inherently sensitive to future supply additions.
-
AI demand is broadening beyond HBM into server DRAM and data-center SSDs. Data-center revenue exceeded USD 25 billion in FQ3, data-center SSD revenue exceeded USD 5 billion and more than doubled sequentially, and Cloud Memory plus Core Data Center generated 61% of group revenue. Micron's September 15 demonstration of a 512GB DDR5 RDIMM, validated on AMD and Intel platforms and scheduled for volume production in the second half of 2027, reinforces the view that memory content per AI server is becoming a structural demand driver rather than a one-product HBM story.
-
Contracts materially improve earnings visibility, but they do not abolish cyclicality. Micron has signed 16 Strategic Customer Agreements, typically through 2030, covering roughly 20% of DRAM volume and one-third of NAND volume; 14 agreements carry about USD 100 billion of cumulative minimum-price revenue and the signed portfolio is expected to bring USD 22 billion of deposits and related financial commitments. These take-or-pay structures should raise the trough, yet only part of revenue is protected by floors or fixed pricing, and ceiling clauses limit upside on certain products.
-
Cash conversion is strong enough to fund the capacity build. Nine-month operating cash flow was USD 45.70 billion and mechanically derived adjusted FCF was about USD 29.1 billion after netting USD 19.60 billion of gross property and equipment spending against USD 2.99 billion of government-incentive proceeds. Cash and short-term investments reached USD 26.02 billion versus USD 5.72 billion of total debt at May 28, 2026. Fiscal 2027 quarterly capex will exceed the roughly USD 10 billion planned for FQ4, but present liquidity and customer deposits reduce financing risk.
-
Valuation is not demanding if even part of the new earnings base persists. The API-observed MUON/USDT price of 984.38 and approximately 1.15 billion guided diluted shares imply about USD 1.13 trillion of equity value. Adding nine-month GAAP EPS of USD 41.40 to the FQ4 midpoint of USD 30.73 gives FY2026 implied GAAP EPS of roughly USD 72.13 and a price-to-earnings ratio of about 13.6 times; annualizing FQ4 alone produces about 8.0 times. The positive stance would weaken if FQ4 revenue fell below USD 49 billion, gross margin missed 84%, or management indicated that contract floors sit materially below a normalized mid-cycle margin.
2. Company Overview, Business Mix, and Core Operating Metrics
Micron designs and manufactures DRAM, NAND and NOR memory and storage products. Its economics are driven by bits shipped, average selling prices, manufacturing cost per bit and product mix. Cloud customers buy HBM and high-capacity server DRAM for accelerators and compute racks; enterprise and hyperscale customers buy data-center SSDs; PC and smartphone makers buy client DRAM, LPDRAM, NAND and managed storage; automotive and industrial customers buy qualified products under longer life cycles. Micron generally sells components and modules directly to original equipment manufacturers and distributors, while the new Strategic Customer Agreements add multi-year volume commitments, price bands and deposits.
The Cloud Memory Business Unit contains HBM and other cloud-facing DRAM. Core Data Center includes conventional server DRAM and data-center SSDs. Mobile and Client covers smartphones, PCs and adjacent consumer platforms. Automotive and Embedded serves vehicles, industrial systems and edge devices. The first two units are now the main profit pool: together they generated USD 25.29 billion of FQ3 revenue and operating margins of 78% and 83%, respectively.
|
FQ3 2026 business
|
Products and customers
|
Revenue
|
Sequential growth
|
Share of group
|
Operating margin
|
Research judgment
|
|
Cloud Memory
|
HBM and high-value DRAM for AI accelerators and cloud platforms
|
USD 13.77bn
|
78%
|
33%
|
78%
|
Primary AI profit engine; HBM4 ramp adds mix upside.
|
|
Core Data Center
|
Server DRAM and data-center SSDs for hyperscale and enterprise
|
USD 11.52bn
|
103%
|
28%
|
83%
|
Fastest sequential growth; SSD mix and scarcity pricing reinforce margins.
|
|
Mobile and Client
|
LPDRAM, client DRAM and NAND for smartphones and PCs
|
USD 11.52bn
|
49%
|
28%
|
86%
|
Pricing offset lower bit shipments; most exposed to consumer elasticity.
|
|
Automotive and Embedded
|
Qualified memory and storage for vehicles, industrial and edge systems
|
USD 4.63bn
|
71%
|
11%
|
75%
|
Longer qualification cycles improve durability, but unit demand remains cyclical.
|
|
Group
|
DRAM, NAND and NOR portfolio
|
USD 41.46bn
|
74%
|
100%
|
80.4%
|
Exceptional profitability is real, but pricing explains more than volume.
|
Note: Group operating margin is GAAP operating income divided by revenue. Business-unit margins are company-reported. Totals may not sum due to rounding.
Core Operating Metrics and Changes
The immediate research trigger is the FQ4 2026 report scheduled for September 30, 2026 at 2:30 p.m. Mountain Time. The company already guides to USD 50.0 billion of revenue, approximately 86% gross margin and GAAP EPS of USD 30.73 at the midpoint. Therefore, a simple beat against stale history is not enough; the market-relevant questions are whether pricing remains firm, how quickly new supply arrives, how much FY2027 capex rises, and whether signed customer contracts turn into deposits and recognized revenue on the expected timetable.
|
Metric or event
|
Latest value
|
Comparison
|
Basis
|
Investment meaning
|
|
FQ3 revenue
|
USD 41.46bn
|
74% QoQ; 346% YoY
|
GAAP, quarter ended May 28, 2026
|
Pricing created most of the acceleration.
|
|
DRAM and NAND
|
76% and 24% of revenue
|
ASP up low-60s and mid-80s QoQ
|
Company technology mix
|
Scarcity is broad across both memory categories.
|
|
FQ3 GAAP gross margin
|
84.6%
|
74.4% in FQ2; 37.7% a year earlier
|
GAAP
|
Extraordinary operating leverage also flags peak-cycle risk.
|
|
FQ3 adjusted FCF
|
USD 18.3bn
|
44% of revenue
|
Company non-GAAP definition
|
Internal funding capacity exceeds current expansion needs.
|
|
FQ4 guidance
|
USD 50.0bn revenue; 86% gross margin; USD 30.73 GAAP EPS
|
21% implied sequential revenue growth
|
Company midpoint
|
A high bar makes forward commentary more important than the headline quarter.
|
|
512GB DDR5 RDIMM
|
Up to 9,200 MT/s; over 60% lower power
|
Volume production in H2 2027
|
Company product disclosure
|
Expands AI memory demand beyond accelerators into CPU server racks.
|
The earnings bridge is directly reproducible. At the FQ4 midpoint, USD 50.0 billion of revenue multiplied by an 86% gross margin produces roughly USD 43.0 billion of gross profit. Subtracting guided GAAP operating expenses of USD 1.86 billion implies about USD 41.14 billion of operating income; after interest, other items and tax, company guidance arrives at USD 30.73 of diluted EPS on approximately 1.15 billion shares. Every one percentage point of gross margin changes quarterly gross profit by roughly USD 500 million before tax, or approximately USD 0.36 per diluted share after applying a 15% illustrative tax rate. That is the key transmission chain from pricing and mix to earnings and valuation.
3. Fundamental Quality
|
Item
|
FY2024
|
FY2025
|
9M FY2026
|
FQ3 2026
|
Research judgment
|
|
Revenue
|
USD 25.11bn
|
USD 37.38bn
|
USD 78.96bn
|
USD 41.46bn
|
AI demand plus pricing produced a step-change, not a normal recovery.
|
|
GAAP gross margin
|
22.4%
|
39.8%
|
76.6%
|
84.6%
|
Current margin is exceptional and should not be capitalized as permanent.
|
|
GAAP net income
|
USD 0.78bn
|
USD 8.54bn
|
USD 47.27bn
|
USD 28.24bn
|
Profit growth is operating leverage rather than accounting adjustments.
|
|
Operating cash flow
|
USD 8.51bn
|
USD 17.53bn
|
USD 45.70bn
|
USD 25.39bn
|
Strong cash conversion despite a USD 19.95bn nine-month receivables build.
|
|
Adjusted FCF
|
About USD 0.4bn
|
USD 3.72bn
|
About USD 29.1bn
|
USD 18.3bn
|
Cash generation now funds capex and deleveraging simultaneously.
|
|
Gross property and equipment spending
|
USD 8.39bn
|
USD 15.86bn
|
USD 19.60bn
|
USD 7.83bn
|
Capital intensity is rising before new greenfield output arrives.
|
|
Cash plus short-term investments / debt
|
USD 8.11bn / USD 13.40bn
|
USD 10.31bn / USD 14.58bn
|
USD 26.02bn / USD 5.72bn
|
Same as period end
|
Balance sheet has moved from net debt to substantial net cash.
|
Note: FY2024 and FY2025 are fiscal years ended in August. Nine-month FY2026 ended May 28, 2026. Adjusted FCF uses operating cash flow less capital expenditures net of government incentives and property-sale proceeds; the 9M FY2026 amount is mechanically derived and rounded.
Growth and margins. The latest growth is primarily price and mix. FQ3 DRAM revenue rose 67% sequentially on low-single-digit bit growth, while NAND revenue rose 99% on mid-single-digit bit growth. This is good evidence of pricing power under scarcity, but it also means earnings are more exposed to future ASP normalization than the revenue growth rate alone suggests.
Cash flow and capital spending. Cash conversion is strong, but receivables rose by USD 19.95 billion over nine months as revenue expanded. Fiscal 2026 capex is expected near USD 27 billion, with quarterly spending above USD 10 billion in FY2027. The quality test is whether customer deposits and operating cash continue to fund construction without rebuilding net debt.
Balance sheet and capital allocation. Micron repaid USD 9.38 billion of debt during the first nine months and held more than USD 20 billion of net cash using cash plus short-term investments. Management intends to increase capital returns after December 9, 2026 and ultimately return excess cash, but capacity investment remains the first claim on funds.
Fundamental conclusion. Fundamental quality is strong and materially better than in prior memory cycles. The single most important variable is the sustainable gross-margin floor embedded in Strategic Customer Agreements once supply improves, not the exact magnitude of the September quarter beat.
4. Industry and Competitive Landscape
The relevant industry is advanced DRAM and NAND, including HBM, server DRAM and enterprise SSDs. DRAM supply is concentrated among Samsung Electronics, SK hynix and Micron; NAND adds Kioxia and Sandisk. In 2026, AI infrastructure spending increased accelerator memory, server capacity and context-storage demand simultaneously. Supply remains constrained by long fab lead times, advanced-packaging capacity, slower bit gains at new process nodes and HBM's larger wafer trade ratio.
|
Competitive dimension
|
Micron position
|
Scale evidence and limitation
|
Main competitors
|
Valuation implication
|
|
AI accelerator memory
|
HBM4 in volume shipment; more than USD 1bn shipped by FQ3
|
Company disclosure; no uniform HBM share denominator
|
SK hynix, Samsung Electronics
|
Qualification and yield execution support premium margins.
|
|
Server DRAM
|
512GB DDR5 RDIMM demonstrated on AMD and Intel platforms
|
Volume begins in H2 2027, so current revenue impact is limited
|
Samsung Electronics, SK hynix
|
Broadens AI content growth beyond HBM.
|
|
Enterprise NAND and SSD
|
Data-center SSD revenue above USD 5bn in FQ3
|
More than doubled QoQ; market-share denominator not disclosed
|
Samsung Electronics, Kioxia, Sandisk, SK hynix
|
NAND is now a profit engine rather than a drag.
|
|
Contract model
|
16 take-or-pay SCAs, usually through 2030
|
About 20% of DRAM volume and one-third of NAND volume
|
SK hynix has LTAs with around 10 customers
|
Greater visibility deserves a higher trough multiple, not a peak multiple.
|
|
Capacity and capital
|
Idaho, New York, Taiwan, Japan and Singapore expansion
|
FQ4 capex about USD 10bn; meaningful new output from 2027
|
All major suppliers are expanding
|
Delayed supply supports near-term pricing but raises 2028 normalization risk.
|
|
Company
|
Latest comparable period
|
Revenue
|
Growth or margin
|
Operating and investment status
|
Competitive conclusion
|
|
Micron Technology Inc.
|
FQ3 2026
|
USD 41.46bn
|
80.4% GAAP operating margin
|
HBM4 ramp, 16 SCAs, USD 27bn FY2026 capex plan
|
Net winner: strongest contract disclosure and exceptional pricing capture.
|
|
SK hynix
|
Q2 2026
|
KRW 79.32tn
|
76% operating margin
|
HBM4 mass shipments began; LTAs with around 10 customers
|
Co-winner and Micron's toughest HBM competitor.
|
|
Samsung Electronics DS
|
Q2 2026
|
KRW 127.5tn
|
About 70% operating margin
|
HBM4 scaled and HBM4E samples shipped; foundry included in DS figures
|
Scale winner, but segment breadth makes memory profitability approximate.
|
|
Kioxia Holdings Corporation
|
Q1 FY2026
|
JPY 1.77tn
|
71.9% IFRS operating margin
|
SSD and Storage revenue JPY 1.17tn; Q2 revenue guided up 35%
|
NAND winner; lacks DRAM and HBM diversification.
|
Note: Periods, currencies and accounting standards differ. Samsung DS includes memory, System LSI and Foundry, so its operating margin is only a directional comparator. Kioxia operates in NAND and reports under IFRS. No currency conversion is used.
All major suppliers are winning from scarcity. SK hynix remains the clearest HBM technology threat, Samsung has the broadest manufacturing scale, and Kioxia is capturing the NAND upswing. Micron is a net beneficiary because it combines DRAM and NAND exposure with unusually detailed take-or-pay contract economics and a rapidly improving balance sheet. The loser is the downstream device customer with weak pricing power: mobile and PC unit demand is already moderating as memory costs rise.
Micron's competitive advantage will narrow if rivals add qualified HBM4 capacity faster or if 2027-2028 greenfield capacity arrives before AI service monetization supports further infrastructure spending. Conversely, successful conversion of 16 SCAs into deposits, revenue and above-cycle floor margins would justify treating Micron as a contracted infrastructure supplier rather than a pure spot-memory producer.
5. Key Risks
-
Peak pricing reverses. If DRAM or NAND ASP growth turns negative while bit growth remains low, revenue and gross profit will fall rapidly because pricing caused most of the recent increase. At FQ4 scale, each one-point gross-margin decline removes about USD 500 million of quarterly gross profit before tax.
-
Strategic Customer Agreements provide less protection than expected. If price floors are materially below current levels, customers contest take-or-pay provisions, or the remaining planned agreements are not signed, the perceived earnings floor and valuation support would weaken.
-
Capacity spending outruns cash returns. Quarterly capex above USD 10 billion in FY2027 could absorb a larger share of operating cash if pricing normalizes. Delays in Idaho, New York, Taiwan, Japan or Singapore would reduce returns while construction cash outflows continue.
-
Technology or yield execution slips. Slower HBM4 yield improvement, delayed HBM4E qualification or weaker 1-gamma DRAM and G9 NAND ramps would shift high-value demand toward SK hynix or Samsung and compress mix.
-
Customer concentration and AI capex slow. Four very large customers and three medium customers represent much of the SCA economics. A slowdown in hyperscaler AI spending, export restrictions or a customer-specific accelerator delay could reduce near-term HBM, server DRAM and SSD demand simultaneously.
-
Consumer elasticity spreads. Mobile and PC unit volumes are already pressured by higher component costs. If device makers reduce memory content or inventories, Micron's 28% Mobile and Client revenue exposure could turn from a pricing beneficiary into a volume headwind.
-
Receivables and working capital weaken cash conversion. Receivables increased by USD 19.95 billion over the first nine months. Slower collections or customer-credit stress would make reported earnings less cash-generative even if margins remain high.
6. Monitoring Checklist
-
FQ4 revenue: above USD 50.0 billion strengthens the thesis; below USD 49.0 billion weakens the pricing and volume bridge.
-
FQ4 GAAP gross margin: 86% or better confirms scarcity economics; below 84% would suggest faster normalization than guidance implies.
-
FQ4 GAAP EPS: compare with the USD 30.73 midpoint, while separating tax and non-operating effects from core margin performance.
-
FY2027 capex and FCF: positive FCF despite quarterly capex above USD 10 billion supports self-funded expansion; a return to net debt would weaken the quality judgment.
-
SCA conversion: track the number of signed contracts, customer deposits toward the disclosed USD 22 billion commitment, and recognized revenue under floor, ceiling or fixed-price terms.
-
HBM4 and HBM4E: monitor yield, customer qualification, shipment growth and whether SK hynix or Samsung gains share on next-generation platforms.
-
Data-center mix: Cloud Memory plus Core Data Center remaining above 60% of revenue would support structural AI exposure; a sharp decline without consumer recovery would weaken growth quality.
-
Working capital: receivables should grow slower than revenue and operating cash flow should remain above 50% of revenue; deterioration would signal lower cash quality.
7. Sources